Unraveling September 15, 2026: The Market Moves That Could Change Your Financial Future Overnight

Just when you thought markets might catch a breather, Tuesday reminds us why financial landscapes never sleep—crude oil prices jetted higher, nudged by fresh security alarms around Saudi Arabia’s key Red Sea export hub. This wasn’t your everyday headline; it stirred the pot enough to catapult the U.S. 10-year Treasury yield to levels not seen since the pre-financial crisis era nearly two decades ago. Stocks, narrowly dodging positive runs, stumbled under the double whammy of climbing energy costs and soaring yields, while Bitcoin took a nosedive after the Senate threw cold water on a pivotal crypto market reform bill. Meanwhile, the dollar flexed its muscle across the board as traders braced for Wednesday’s Federal Reserve decision. Makes you wonder: when geopolitics, energy, and monetary policy clash like this, what’s the real story beneath the surface? Dive into the latest twists and turns you might’ve missed in the forex and economic realm today. LEARN MORE.
A fresh jump in crude oil set the tone on Tuesday, as new security alerts around Saudi Arabia’s main Red Sea export port piled onto an already tense Middle East backdrop and pushed the U.S. 10-year Treasury yield to its highest in nearly two decades.
Stocks slipped for the sixth time in seven sessions under the weight of higher yields and pricier energy, and Bitcoin broke from the pack, sinking after the Senate blocked a landmark crypto market-structure bill. The dollar firmed against every major with a Federal Reserve rate decision now a day away.
Check out the forex news and economic updates you may have missed in the latest trading session!
News Headlines & Data:
- U.S. attacked Iranian boats trying to seize Navy drone
- New Zealand Electronic Card Retail Sales for August 2026: -0.9% (-0.7% forecast; 1.3% previous)
- China Unemployment Rate for August 2026: 5.3% (5.2% forecast; 5.2% previous)
- China Retail Sales for August 2026: 0.4% y/y (1.0% y/y forecast; 0.6% y/y previous)
- China Industrial Production for August 2026: 5.2% y/y (5.0% y/y forecast; 4.5% y/y previous)
- Germany Wholesale Prices for August 2026: 6.8% y/y (6.2% y/y forecast; 5.3% y/y previous); 0.9% m/m (0.3% m/m forecast; 0.2% m/m previous)
-
U.K. Employment Change for July 2026: 67.0k (70.0k forecast; 83.0k previous)
- U.K. Unemployment Rate for July 2026: 4.9% (5.0% forecast; 4.9% previous)
- U.K. HMRC Payrolls Change for August 2026: -26.0k (-4.0k forecast; -13.0k previous)
- U.K. Claimant Count Change for August 2026: 27.8k (5.0k forecast; -11.0k previous)
- France Inflation Rate for August 2026: 2.4% y/y (2.4% y/y forecast; 2.1% y/y previous)
- Germany ZEW Economic Sentiment Index for September 2026: 34.7 (34.0 forecast; 34.2 previous)
- U.S. ADP Employment Change Weekly for August 29, 2026: 16.25k (12.0k previous)
- Canada Wholesale Sales Final for July 2026: 0.3% m/m (-0.6% m/m forecast; 2.8% m/m previous)
- Canada New Motor Vehicle Sales for July 2026: 176.2k (190.1k forecast; 190.2k previous)
- U.S. NY Empire State Manufacturing Index for September 2026: 7.6 (14.0 forecast; 20.6 previous)
- New Zealand Global Dairy Trade Price Index for September 15, 2026: -1.1% (0.9% previous)
Broad Market Price Action:
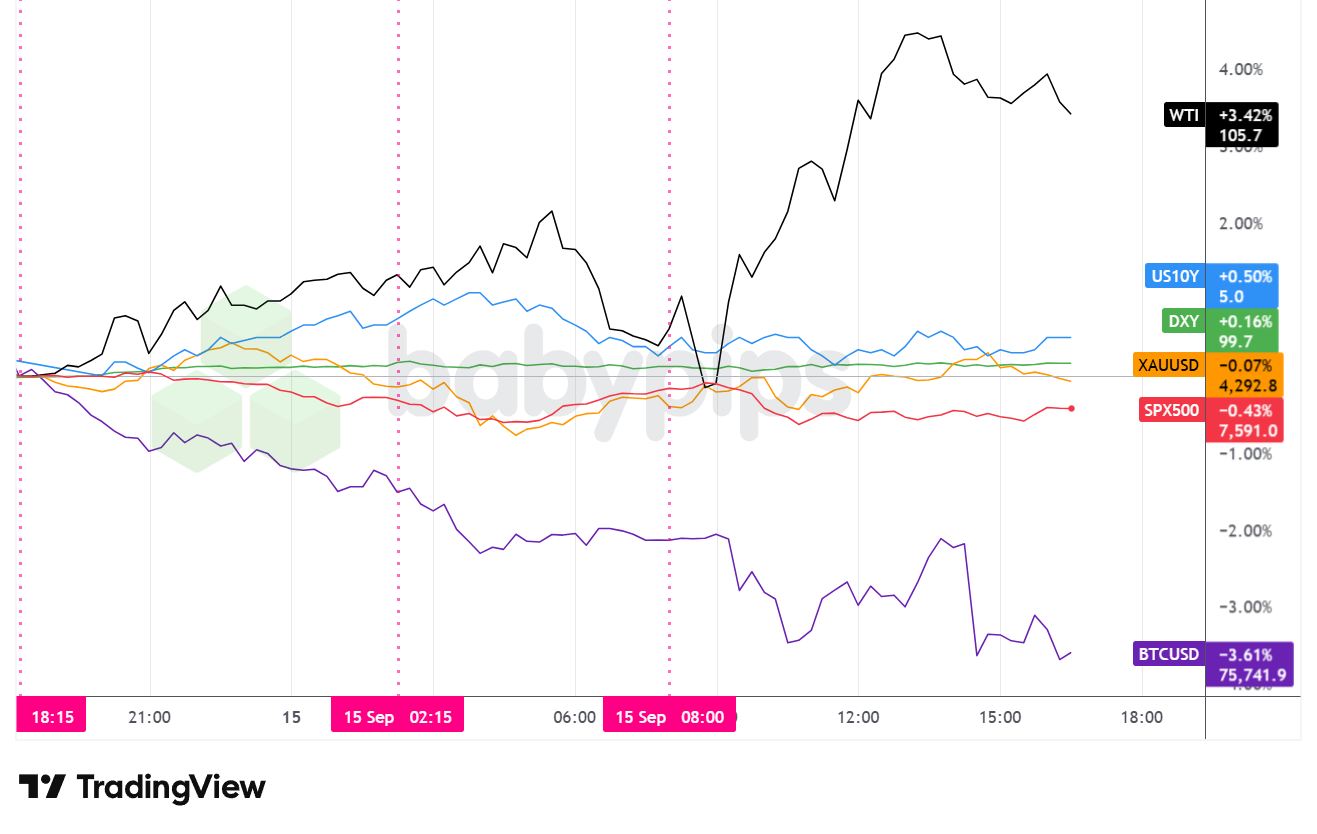
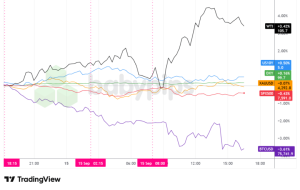
Dollar Index, Gold, Oil, S&P 500, U.S. 10-yr Yield, Bitcoin Overlay – Chart Faster With TradingView
The overlay shows crude and yields leaning higher while stocks and Bitcoin gave ground, with gold pinned near the flatline. One macro force sat underneath all of it, since a rising oil price feeds inflation worry, that worry lifts Treasury yields, and higher yields pull money away from stocks and non-yielding assets. The split hardened once U.S. traders arrived to fresh supply-risk headlines and a wall of Fed-hike pricing.
Oil did the day’s heavy lifting. WTI crude climbed around 3.4% to trade near $106, with Brent pushing above $108, after Saudi Arabia’s Civil Defence issued danger alerts for six cities that included Yanbu, the kingdom’s main Red Sea export port, before later declaring the threat had passed. The alerts landed amid a run of Houthi strikes on Saudi territory and a day after U.S. forces destroyed two Iranian boats that had tried to grab a Navy drone in the Strait of Hormuz. Crude ground higher from the London morning, pulled back, and then accelerated higher through the U.S. session, tagging its peak near $106.70 in the early afternoon before easing back a touch into the close.
The 10-year Treasury yield pushed to its highest in nearly two decades. It rose as high as roughly 5.03% during European hours, a level last seen around 2007, before slipping back toward 5.0% as buyers stepped in near the milestone. Surging crude and hotter inflation expectations drove the climb, and swelling government and corporate borrowing needs added to the pressure. With yields near 5%, cash and short-dated debt now offer real competition to equities, which gives stock buyers another reason to hold back ahead of Wednesday’s Fed decision.
The S&P 500 slipped around 0.4% to finish near 7,591, its sixth lower close in seven sessions, while the Nasdaq 100 dropped about 0.6%. The index leaked lower from the London open into the U.S. morning, bottoming near 7,575 before steadying in the afternoon. Firmer yields and the fresh climb in oil kept buyers cautious, and a fading appetite for risk assets, flagged in a Bank of America fund manager survey that showed managers trimming equity exposure, did little to help the mood.
Gold ended close to flat, easing less than 0.1% to trade near $4,293. The metal caught an early haven bid in Asia and pushed toward $4,314, then leaked back below $4,265 through the London morning as a firmer dollar and rising real yields outweighed the geopolitical pull, before clawing back most of the drop during the U.S. afternoon. A tense Middle East backdrop did not translate into a lasting gold rally this time, a reminder that higher real yields can blunt the haven trade even when the headlines look supportive.
Bitcoin broke from the rest of the tape, sliding about 3.6% to trade near $75,700 and sitting at the bottom of the overlay. It drifted lower through Asia and London, then slumped below $75,000 in the U.S. afternoon after the Senate blocked a long-stalled crypto market-structure bill in a procedural vote, a setback that also dragged crypto-linked stocks sharply lower. With no supportive catalyst to lean on and a defensive macro mood already in place, the failed vote gave sellers a clear reason to press.
FX Market Behavior: U.S. Dollar vs. Majors
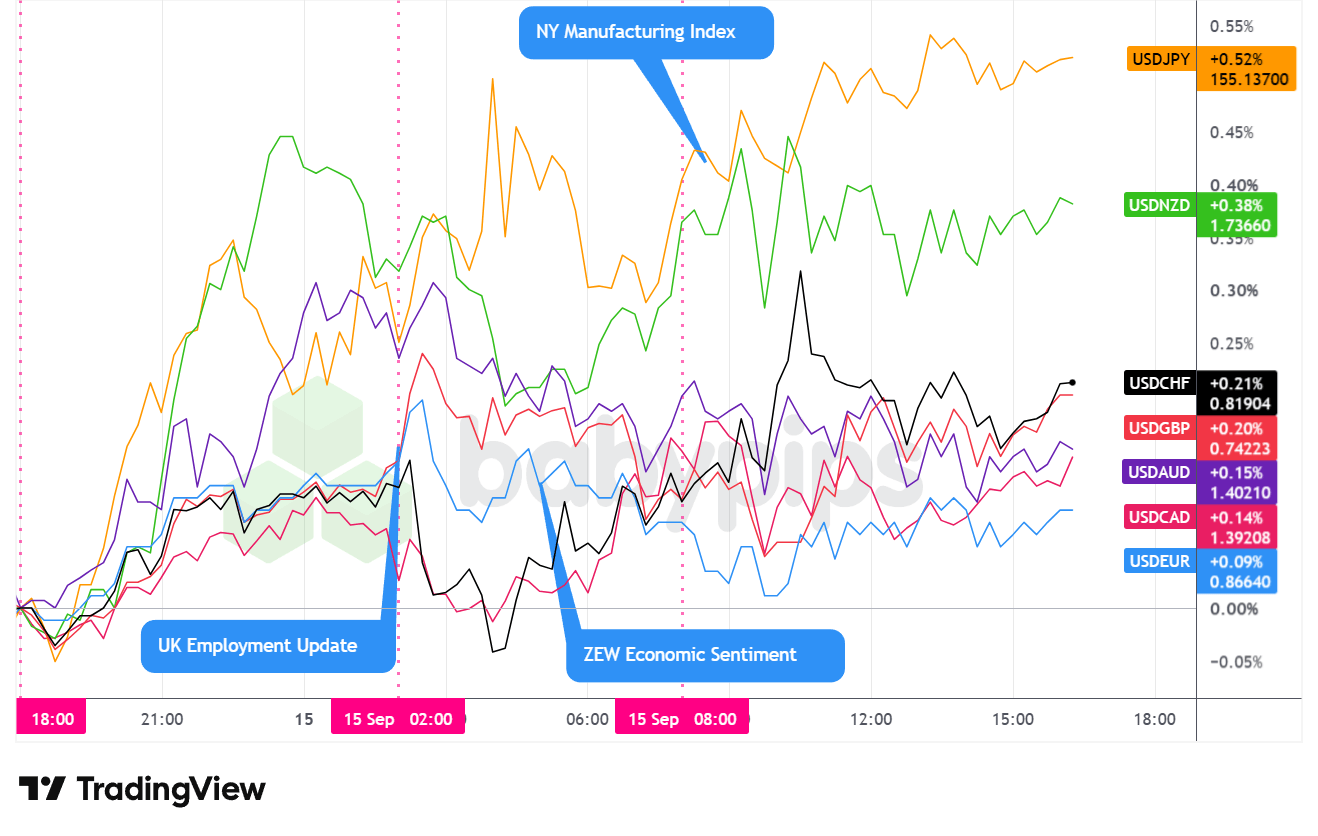
Overlay of USD vs. Major Currencies – Chart Faster With TradingView
The dollar gained on every major on Tuesday, with the Dollar Index adding around 0.2% to trade near 99.7. Rising Treasury yields and steady Fed-hike bets did most of the work, and the greenback carried a firm tone from the Asian reopen through to the close. The moves stayed modest in size, which fits a market reluctant to commit before Wednesday’s decision.
Through the Asian session, the dollar firmed across the board as the 10-year yield climbed back toward 5% and oil held its bid. USD/JPY pushed from near 154.3 up toward 154.9, and the antipodeans sat at the soft end of the board after mixed Chinese data: industrial production beat, but retail sales and fixed-asset investment missed and home prices kept falling. That combination likely weighed on the growth-sensitive Aussie and, more sharply, the Kiwi, which also had a weak dairy auction to contend with.
The London session turned quieter, with the dollar holding gains rather than extending them. The U.K. jobs report offered the standout release: unemployment held at 4.9% and beat forecasts, but payrolls fell by 26,000, more than five times the drop economists expected. The pound softened modestly on the payrolls miss without breaking down. Euro-area ZEW sentiment then came in at 25.8 against a 38.0 forecast, a sizable miss, yet the euro proved the most resilient major, slipping just 0.1% against the dollar.
Momentum picked back up in the U.S. session. The NY Empire State manufacturing index missed at 7.6 against a 14.0 forecast, a soft read that did little to slow the dollar. USD/JPY tagged its session high near 155.17 as the yen stayed at the back of the field, leaving it the weakest major on the day. By the close the dollar had held its gains across the board, with the yen and Kiwi the laggards and the euro and pound the most resilient. The through-line ran beneath the currencies rather than within them, as oil, yields, and the Fed countdown set the tone, and traders look set to stay reactive to that mix into the decision.
Upcoming Potential Catalysts on the Economic Calendar
- U.S. API Crude Oil Stock Change for September 11, 2026 at 8:30 pm GMT
- New Zealand Westpac Consumer Confidence for September 30, 2026 at 9:00 pm GMT
- Japan Balance of Trade for August 2026 at 11:50 pm GMT
- Japan Machinery Orders for July 2026 at 11:50 pm GMT
- Australia Westpac Leading Index for August 2026 at 1:00 am GMT
- U.K. Inflation Updates for August 2026 at 6:00 am GMT
- Euro area Industrial Production for July 2026 at 9:00 am GMT
- Euro area Labour Cost Index & Wage Growth Final for June 30, 2026 at 9:00 am GMT
- 30-Year Mortgage RateU.S. MBA Mortgage Applications & for September 11, 2026 at 11:00 am GMT
- Canada Building Permits for July 2026 at 12:30 pm GMT
- U.S. Import & Export Prices for August 2026 at 12:30 pm GMT
- U.S. Retail Sales for August 2026 at 12:30 pm GMT
- U.S. NY Fed Services Activity Index for September 2026 at 12:30 pm GMT
- ECB Elderson Speech at 1:00 pm GMT
- U.S. NAHB Housing Market Index for September 2026 at 2:00 pm GMT
- EIA Crude Oil Stocks Change for September 11, 2026 at 2:30 pm GMT
- ECB President Lagarde Speech at 5:00 pm GMT
- Bank of Canada Summary of Deliberations at 5:30 pm GMT
-
Federal Funds Rate for September 16, 2026 at 6:00 pm GMT
- U.S. FOMC Economic Projections at 6:00 pm GMT
- U.S. Fed Press Conference at 6:30 pm GMT
Everything funnels into Wednesday’s Fed decision, where money markets lean toward a quarter-point hike that would lift the benchmark rate to 4.00%. The dot plot and Chair Warsh’s press conference matter as much as the move itself, since traders want to know how far the tightening runs.
Ahead of that, U.K. inflation and U.S. retail sales offer earlier tests of the growth-versus-inflation tug of war, but neither is likely to outweigh the oil tape and the long end of the Treasury curve, which have set the direction all week. Positioning looks set to stay cautious and headline-driven into the announcement.
Tuesday’s market action showed oil surging on geopolitical tensions, Treasury yields climbing to 2007 highs, stocks sliding, and the dollar firming, but most traders watching each market separately miss why they all moved together. Premium members can read our lesson:
📖 What Is Intermarket Analysis?
Reading this helps you understand how commodities, bonds, equities, and currencies interconnect, why a single-asset view misses critical context, and how to read the cross-asset ripple effects that drive currency moves before they show up on your chart.
And if you’re not a Premium subscriber yet, consider joining.
With Babypips Premium, you get full access to School of Pipsology lessons that help you understand not just what moved today, but how oil prices, yield curves, equity flows, and currency strength all feed into one another.



Post Comment