Chainalysis Uncovers $457B Crypto Tax Gap—Why CARF Could Be Missing the Biggest Scoop Yet

Imagine trying to catch tax on $457 billion worth of onchain crypto activity worldwide in 2025—sounds like trying to net a school of slippery fish with a teacup, right? Well, according to a fresh Chainalysis report, that’s pretty much the scale we’re dealing with, but here’s the kicker: current international rules might only reel in a tiny fraction of it. The U.S. alone racks up a hefty $112.6 billion slice, with North America and the European Union leading the charge. What’s fascinating is that these numbers capture gains from mining, staking, lending, and crypto payments—excluding the usual centralized exchange trades. Yet, only about 14% of this crypto dance gets reported under the OECD’s Crypto-Asset Reporting Framework (CARF)—leaving a whopping 86% playing hide and seek across decentralized platforms and peer-to-peer transfers. Makes you wonder—is our global tax net big enough, or is most of this crypto just ghosting the system? Dive into the maze of onchain activity and reporting challenges to see why the taxman’s job is just getting trickier. LEARN MORE.
Potentially taxable onchain crypto activity reached at least $457 billion globally in 2025, while international reporting rules may capture only a fraction of it, according to a new Chainalysis report.
The US accounted for an estimated $112.6 billion of the total, while North America led all regions with $134.6 billion, followed by the European Union at $125.1 billion.
The estimates include realized gains, income from activities such as mining, staking and lending, and crypto-denominated payments across six major blockchains, but exclude trading and other activity conducted within centralized exchanges.
Chainalysis said transactions covered by the Organisation for Economic Co-operation and Development’s (OECD) Crypto-Asset Reporting Framework (CARF) account for just 14% of the onchain taxable activity it identified. The remaining 86% includes activity on decentralized exchanges, peer-to-peer transfers, onchain income streams and payments.
CARF, developed by the OECD in 2022, requires covered crypto service providers to report customer transaction data to tax authorities.
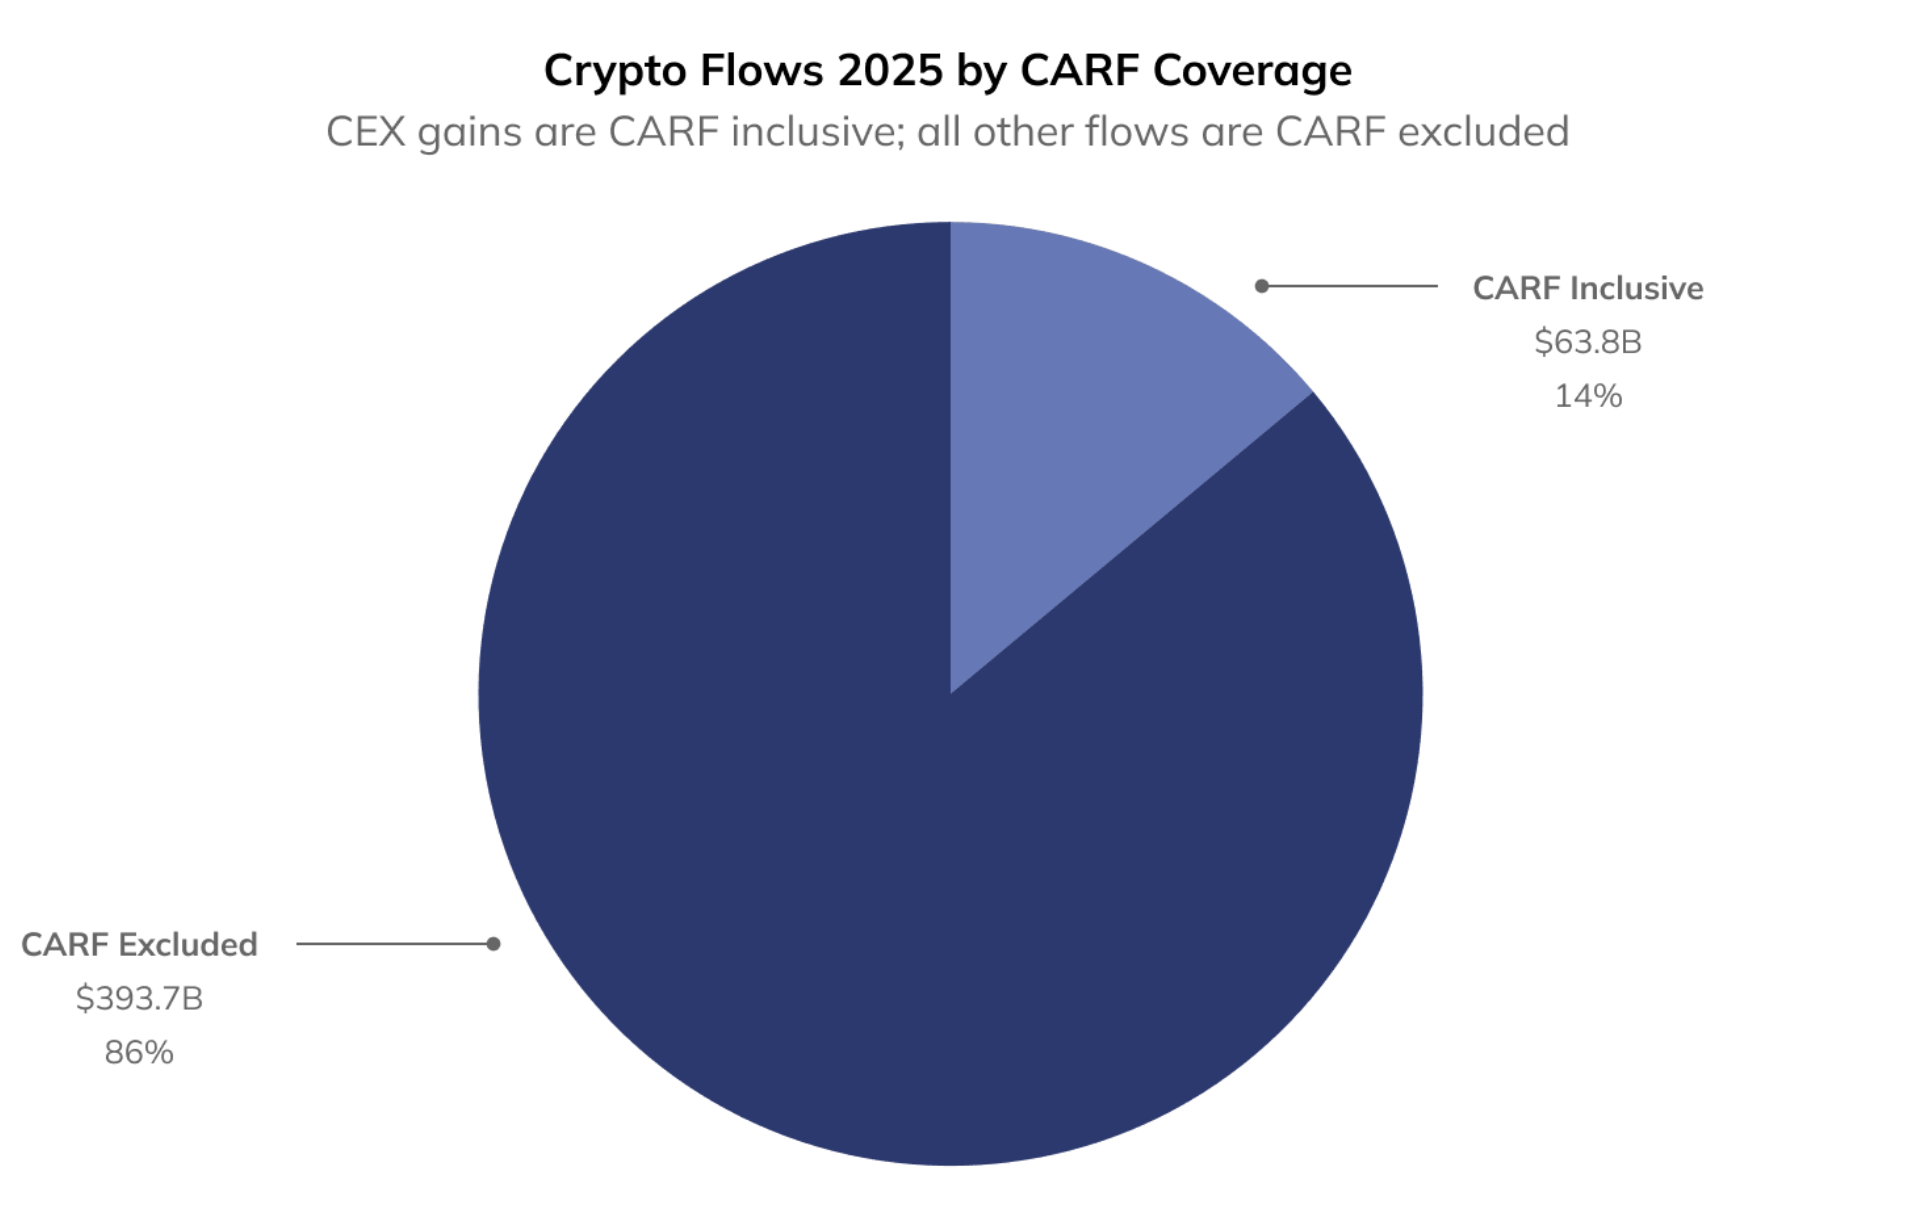
CARF covers only 14% of potentially taxable onchain crypto activity.
Source: Chainalysis
Related: Chainalysis sues US over $95M ICE contract with TRM Labs
CARF’s limits on onchain tax reporting
CARF data collection began on Jan. 1, 2026, in 48 jurisdictions, including the United Kingdom and European Union, requiring covered crypto platforms to collect additional customer and tax residency information.
Under CARF, in-scope crypto providers collect customer and tax residency information and report transaction data to domestic tax authorities, which can then share that information across borders.
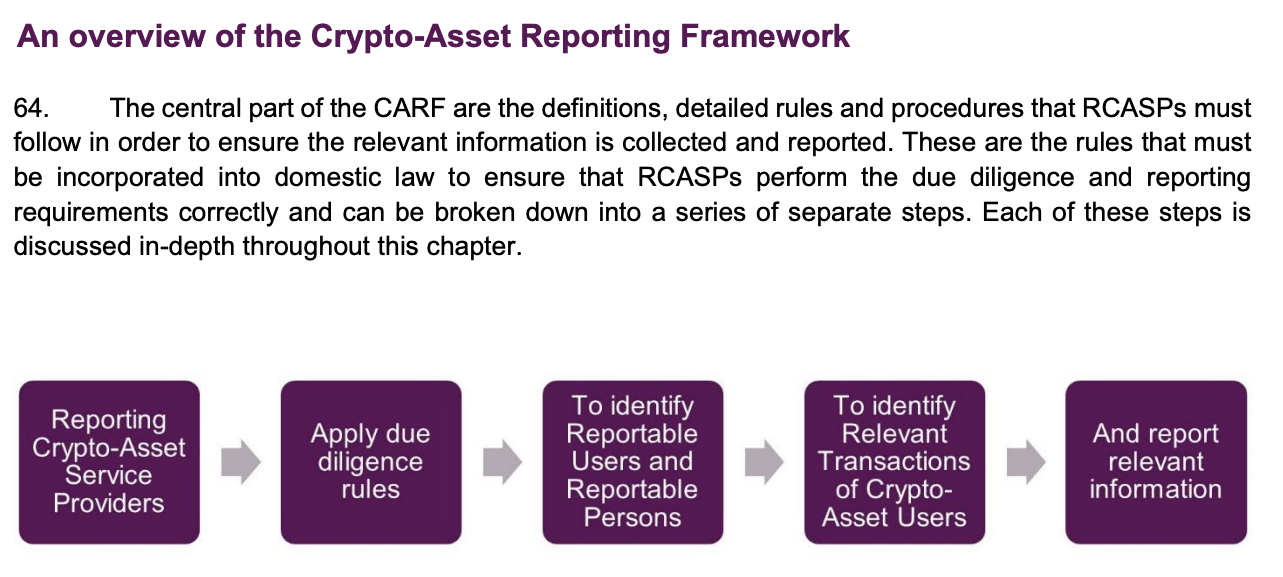
CARF framework. Source: OECD
CARF’s focus on crypto intermediaries also helps explain the gaps highlighted by Chainalysis. Colby Mangels, a former OECD adviser who worked on CARF, told Cointelegraph in January that the framework was designed around intermediaries that facilitate crypto transactions as a business.
Much of decentralized finance therefore remains outside the reporting perimeter, as there may be no centralized operator or custodial relationship on which to impose reporting requirements.
That could change as regulators develop rules for decentralized platforms. Mangels said tax authorities are watching developments in anti-money laundering regulation, including efforts to determine when DeFi platforms or their operators should be treated as regulated crypto service providers.
Magazine: SEC’s proposed crypto rules probably won’t spark new ICO boom


Post Comment